FG Unveils Digital Financial Monitoring System to Boost Agricultural Investment, Support Smallholder
By Atlantic Reports
The Federal Government has unveiled a digital financial monitoring system and proposed innovative financing mechanisms aimed at attracting private investment into Nigeria's agricultural sector, improving access to affordable credit and strengthening accountability in agro-industrial development.
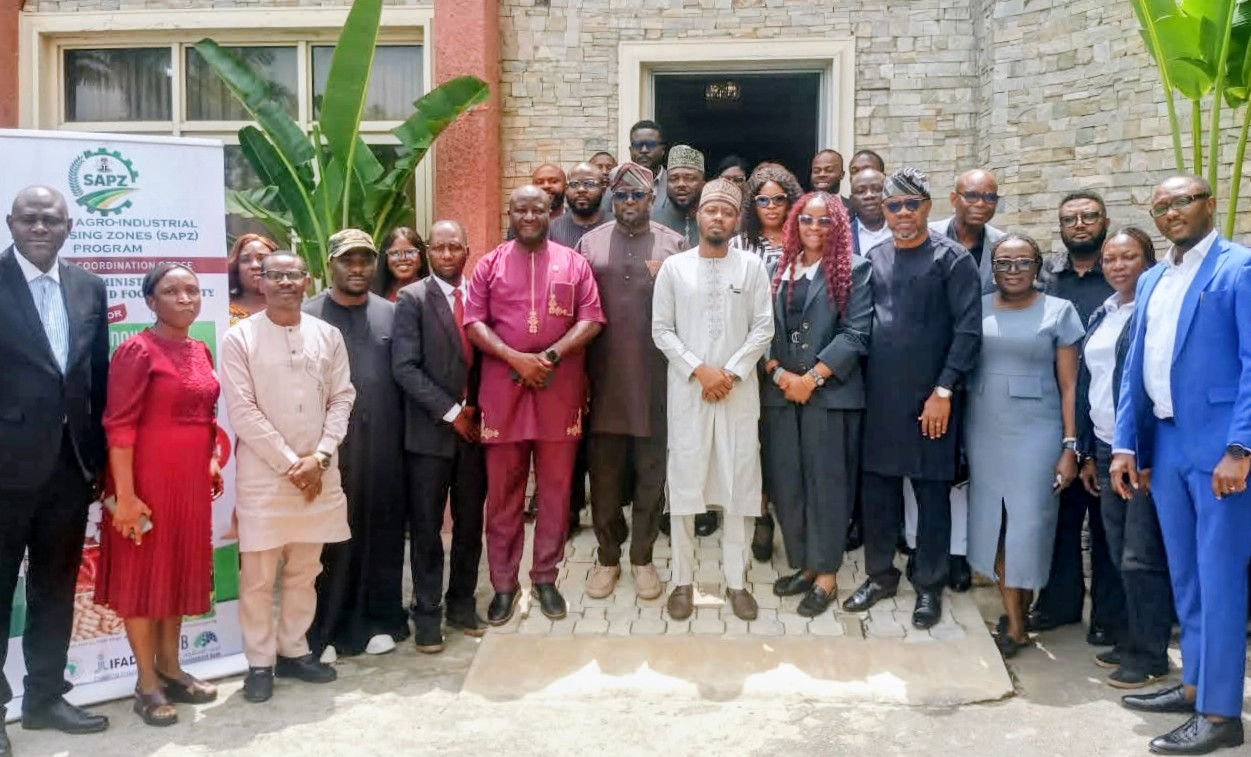
The initiatives, introduced under the Special Agro-Industrial Processing Zones (SAPZ) Programme, were presented on Thursday, October 8, 2026, during a validation workshop in Abuja.
The programme seeks to address longstanding challenges that have limited agricultural productivity and investment, particularly the high cost of borrowing, inadequate insurance coverage, infrastructure deficits and financial risks confronting smallholder farmers and agribusiness operators.
At the centre of the initiative is the Digital Financial Flow Monitoring System (DFFMS), designed to track financial transactions, investment flows and beneficiaries within the SAPZ ecosystem.
The government expects the system to improve transparency, strengthen investor confidence and support better decisions about how agricultural development funds are allocated and utilised.
Connecting Farmers, Processors and Investors
Speaking at the workshop, the SAPZ National Programme Coordinator, Dr Kabir Yusuf, explained that the programme was designed to go beyond the construction of agricultural processing facilities.
According to him, its broader objective is to establish an integrated economic system connecting farmers, processors, traders, financial institutions and private investors with sustainable markets.
Yusuf described SAPZ as a government-enabled, private-sector-led agricultural production and processing model built around designated industrial zones.
These zones are intended to provide shared infrastructure, supportive government policies and services that allow agribusinesses to operate more efficiently and competitively.
He explained that developing processing infrastructure without ensuring access to suitable financing would limit the programme's economic potential.
For farmers and processors, the challenge is not simply finding markets for agricultural products but securing sufficient capital to expand production, acquire equipment, improve storage and meet processing requirements.
The coordinator maintained that financial institutions and private investors must therefore become active participants in the programme's development.
High Interest Rates, Insurance Costs Remain Major Barriers
Yusuf identified the cost of agricultural financing as one of the major obstacles preventing farmers and agribusinesses from expanding their operations.
He explained that commercial banks and insurance companies already provide financial services to agricultural businesses, but their products often come at costs beyond the reach of smallholder farmers.
Agriculture faces several categories of risk, including unpredictable weather, production losses, fluctuating market prices, operational challenges and regulatory uncertainty.
These risks can discourage financial institutions from lending to farmers or lead them to impose borrowing conditions that many agricultural producers cannot satisfy.
Yusuf noted that banks and insurance providers frequently consider sectors such as petroleum and information technology more attractive because of their perceived investment profiles.
He argued that government intervention was necessary to create conditions that would encourage lenders and insurers to serve agricultural enterprises at more affordable rates.
“The effort is also to ensure banks equally provide lower lending rates and higher appetite to lend,” he said.
The coordinator explained that the proposed financial products would be developed in collaboration with banks, insurance companies and private-sector stakeholders.
The objective is to introduce risk-sharing arrangements that could reduce the financial exposure of lenders while making agricultural credit and insurance more accessible.
However, the presentation did not specify the proposed lending rates, insurance premiums or eligibility requirements that would apply to participating farmers.
These details will be important in determining whether the initiative delivers meaningful financial relief to small agricultural businesses.
Digital Platform to Track Agricultural Investments
A major component of the programme is the Digital Financial Flow Monitoring System, which is intended to improve oversight of investment and financing activities within the designated agro-industrial zones.
Yusuf explained that increasing financial transactions across the SAPZ ecosystem would require reliable information about the movement and utilisation of funds.
“This will address where funds are coming from, where they are going, who is benefitting and what results they are generating,” he said.
The proposed system is expected to support financial tracking, accountability and data-driven investment decisions.
It could also provide programme managers and participating institutions with information needed to identify funding gaps, assess investment performance and monitor the distribution of financial support.
For agricultural development programmes involving public institutions, private investors and financial service providers, effective monitoring is particularly important in reducing the risk of misallocation and ensuring that intended beneficiaries are reached.
Nevertheless, the availability of a digital monitoring platform does not automatically guarantee transparency.
Its effectiveness will depend on the accuracy of information entered, the quality of independent oversight, the accessibility of relevant reports and the safeguards established to prevent manipulation or misuse of financial data.
Will Smallholder Farmers Benefit?
One of the most important tests of the initiative will be whether its financial products reach smallholder farmers, who form a substantial part of Nigeria's agricultural production system.
Many small-scale producers face difficulties accessing formal credit because they lack acceptable collateral, reliable financial records or sufficient protection against crop losses.
Women farmers, rural cooperatives and young agricultural entrepreneurs may face additional barriers to accessing financial services and investment opportunities.
The proposed risk-sharing mechanisms could help address some of these challenges if participating institutions develop affordable products with realistic repayment conditions.
Access to financing could allow farmers to invest in improved inputs, irrigation, storage, mechanisation and other productivity-enhancing services.
For processors, improved financing could support equipment purchases, expansion of processing capacity and stronger connections with agricultural producers.
However, the government has not yet provided detailed information about how beneficiaries will be selected, whether financing will be available to farmers outside designated processing zones or how smaller producers will be protected from exclusion.
Such questions will be central to assessing the programme's inclusiveness and its potential impact on rural livelihoods.
Private Sector Participation Central to Programme
Yusuf emphasised that the success of SAPZ would depend on effective cooperation between government institutions and private investors.
He explained that public authorities were expected to provide enabling infrastructure and policies, while private businesses would drive agricultural production, processing and commercial activities.
“We need to ensure that the private sector is carried along and the ecosystem is properly supported by government,” he said.
The approach seeks to encourage investment in value-added agricultural processing rather than limiting economic activity to the production and sale of raw commodities.
By linking agricultural production with processing facilities and markets, the programme aims to improve efficiency and create opportunities across agricultural value chains.
However, the extent of private-sector participation will depend on factors including infrastructure reliability, financing conditions, market demand and confidence in the programme's governance.
Consultants Highlight Investment Transparency
Earlier, the SAPZ Head of Rural Institutions Development, Abel Ameh, commended stakeholders for their contributions to the programme.
He acknowledged their support for agricultural investment, financial inclusion, private-sector participation and the development of the digital monitoring system.
Ameh said collaboration among participating institutions remained important to achieving the programme's objectives.
Also speaking, the Lead Consultant at Ace Axis Limited, Dr Ifeanyi Maduechesi, presented the proposed financial products and the Digital Financial Flow Monitoring System.
Ace Axis Limited was engaged to develop the financing mechanisms and monitoring platform.
Maduechesi explained that the system was intended to improve investment decision-making by providing more reliable information about financial activities within the agricultural sector.
He maintained that stronger monitoring arrangements would promote transparency and improve the management of agricultural investments.
Implementation and Accountability Remain Critical
Although the initiative represents an effort to address agricultural financing challenges, several important implementation questions remain unanswered.
The information presented at the workshop did not establish the total cost of developing and operating the monitoring platform, the number of participating financial institutions or the volume of financing expected to become available.
It also did not clarify whether the proposed financial products had received final approval, when farmers could begin accessing them or which institutions would be responsible for independently verifying financial records.
The distinction between unveiling a system and demonstrating its operational effectiveness is particularly important.
For the programme to deliver measurable results, authorities will need to establish clear performance indicators covering credit accessibility, insurance affordability, private investment, beneficiary participation and agricultural productivity.
Public reporting on these outcomes would help determine whether the intervention is improving financial inclusion or merely expanding administrative processes.
From Agricultural Investment to Rural Prosperity
Nigeria's agricultural sector faces interconnected challenges involving financing, infrastructure, processing capacity and market access.
The SAPZ initiative seeks to address these problems through coordinated investment, shared facilities and stronger financial partnerships.
For rural communities, the potential benefits extend beyond access to loans.
Successful agro-industrial development could create employment opportunities, support local enterprises, reduce post-harvest losses and improve market access for agricultural producers.
However, these outcomes will depend on effective implementation, affordable financing and sustained support for the farmers and businesses expected to participate.
The newly unveiled financial monitoring system provides a proposed mechanism for improving oversight, but its value will ultimately be measured by the quality of financial information it produces and the development outcomes it helps achieve.
For Nigeria's smallholder farmers, the central question remains whether the initiative will translate into affordable credit, accessible insurance, stronger markets and better livelihoods.
Atlantic Reports: Voices. People. Facts.
Written by
Atlantic Reports Admin
Comments
- Be the first to comment.