Africa’s Instant Payment Push Faces Test of Cost, Access and Consumer Trust
By Atlantic Reports
Africa’s push for faster digital payments faces a challenge beyond transaction speed: ensuring that people can afford the services, use them across different providers and obtain help when money goes missing.
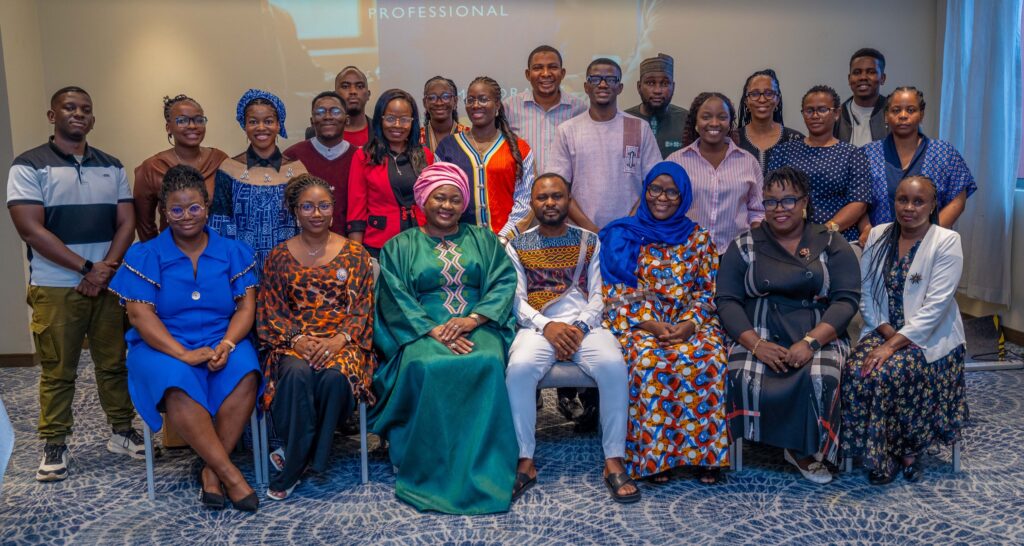
These concerns shaped discussions at a three-day workshop organised by the AfricaNenda Foundation in Nairobi, Kenya, where participants examined how instant payment systems could better serve individuals, small businesses and underserved communities.
The workshop brought together 18 journalists and three participants from the African Union Commission. Its focus extended beyond payment infrastructure and transaction volumes to the experiences of people using, or struggling to access, digital financial services.
AfricaNenda, an African nonprofit organisation, works to advance inclusive instant payment systems through greater accessibility, affordability and connectivity between financial service providers.
Sabine Mensah, the foundation’s Deputy Chief Executive Officer, framed the central question:
“Can consumers access the right information and conduct transactions easily, simply, affordably, anytime, anywhere, and instantly?”
A phone does not guarantee financial access
Data presented at the workshop indicated that about 75 per cent of African adults owned mobile phones, while 58 per cent had a bank or mobile money account. Separate figures presented suggested that roughly half of adults used mobile payments.
The figures pointed to a gap between access to mobile technology and participation in digital finance. However, the material supplied did not identify the underlying datasets or reference years, limiting direct comparisons.
John Muthiora, AfricaNenda’s Technical Payment Specialist, said inclusive systems needed to connect different categories of licensed financial institutions.
He explained that separate agreements between banks, mobile money operators and other providers could increase connection costs and operational demands.
A multilateral system, he said, allowed an institution to connect once and transact with several participating providers.
“Multilateral in this sense means one gives you access to many,” Muthiora said.
Such arrangements could connect banks, mobile money operators, fintech companies and microfinance institutions, reducing the complexity of moving money between providers.
But connectivity alone would not ensure inclusion.
Muthiora said payment systems also needed to accommodate basic mobile phones, particularly in rural communities where smartphones, electricity and reliable internet access could be limited.
For users in these communities, the practical test would be whether services remained accessible through the devices and financial institutions they already used.
Nigeria leads workshop assessment
The workshop examined AfricaNenda’s framework for assessing instant payment systems across three levels: basic, progressed and mature.
Serge Ambadiang, the foundation’s Partnership, Advocacy and Capacity Building Specialist, said the assessment covered 36 domestic and regional systems.
Of these, 15 were classified as basic, 10 as progressed and 10 remained unrated. Nigeria’s NIBSS Instant Payment system was identified as the only system rated mature under the framework presented.
NIBSS, the Nigeria Inter-Bank Settlement System, provides payment infrastructure connecting participating financial institutions.
The classification reflected AfricaNenda’s assessment criteria. It did not establish that every Nigerian user enjoyed affordable access, reliable service or satisfactory complaint resolution.
Ambadiang said basic systems generally supported person-to-person and merchant payments but lacked some of the wider connectivity and governance arrangements required for further development.
Progress towards maturity, he explained, required broader transaction uses, effective complaint and redress mechanisms, and sustainable funding models that kept services affordable.
Cross-border fragmentation carries a cost
Participants also examined the difficulties of transferring money between countries with different currencies, regulations and payment infrastructure.
A feasibility study discussed at the workshop estimated that currency conversion through the US dollar or other intermediary currencies could cost about US$5 billion annually in cross-border payments.
It also estimated potential annual fee savings of about US$1 billion across 100 million transfers if charges fell to a three per cent target.
These were study estimates, rather than documented savings already achieved. The supplied material did not include the assumptions or methodology needed to assess them independently.
For businesses trading across borders, lower payment costs and fewer transfer obstacles could make it easier to receive money from customers and pay suppliers. For households, reduced fees could leave recipients with more of the money sent to them.
Dr Patrick Olomo, Head of Economic Policy and Sustainable Development at the African Union Commission, said the commission and AfricaNenda had worked since 2023 towards regulatory harmonisation.
The objective, he explained, was to help existing payment systems work together effectively.
“One of the fundamental challenges that we have is that there is so much fragmentation and so much friction on the regulatory side of things,” he said.
Olomo said common rules and regulatory understanding were necessary across the African Union’s 55 member states and approximately 40 central banks.
Common rules need enforceable commitments
Jacqueline Jumah, AfricaNenda’s Director of Advocacy and Capacity Development, said a feasibility study had found regulatory harmonisation legally, technically, institutionally and economically achievable.
Implementation, however, would require appropriate governance, connected systems and a phased approach reflecting differences in countries’ digital development.
She identified eight priorities: licensing and passporting, interoperability standards, anti-money laundering and customer due diligence, consumer protection, data governance, supervisory cooperation, settlement and liquidity, and a binding African Union instrument.
“Without an enforceable continental basis, the other seven can remain voluntary and uneven,” Jumah said.
Her remarks highlighted the distinction between agreeing on shared ambitions and establishing rules that participating countries and institutions would implement.
Fast transfers require effective protection
The same speed that makes instant payments useful can complicate efforts to recover stolen money.
“Fraudsters exploit the same speed that makes instant payments convenient,” Mensah warned.
She distinguished scams in which users were manipulated into approving transfers from unauthorised fraud, where criminals accessed accounts or credentials and initiated payments without the account holder’s knowledge.
Recovery could become difficult when funds reached recipients within seconds and were withdrawn immediately, she said.
Mensah outlined possible safeguards, including recipient verification, real-time fraud monitoring, information-sharing between providers and clearer reimbursement arrangements.
She also called for consumer education as criminals used impersonation, social engineering and artificial intelligence to deceive users.
Ambadiang said effective consumer recourse was among the more challenging criteria in assessing payment system maturity.
Users needed to know where to complain, how quickly cases would be resolved and what options remained when providers failed to address grievances.
Reporting the experience behind the numbers
AfricaNenda’s Media Lead, Jude Fuhnwi, said the workshop sought to improve journalists’ understanding of instant payments and strengthen public reporting.
He urged participants to examine how systems performed outside major urban centres, where network problems, costs and limited access could undermine their usefulness.
Fuhnwi said participants would join the foundation’s media coalition, which he described as a network for learning and independent story development. He encouraged journalists to examine information from commercial banks and other sources rather than relying solely on AfricaNenda’s reports.
For Africa’s digital payment ambitions, the questions remain practical: who can use the systems, what transactions cost, whether money reaches its destination reliably and how users are protected when something goes wrong.
The workshop’s proposals point towards wider connectivity and common rules. Their value to households and businesses will depend on implementation and measurable improvements in everyday transactions.
Atlantic Reports: Voices. People. Facts.
Written by
Atlantic Reports Admin
Comments
- Be the first to comment.