Tribunal Dismisses CTIN's Appeal, Upholds N2bn Tax Assessment
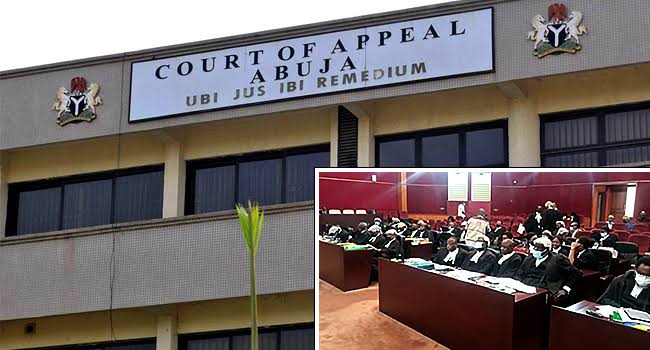
The Tax Appeal Tribunal sitting in Abuja on Thursday ordered the Cement Technology Institute of Nigeria (CTIN) to pay the Nigeria Revenue Service (NRS), formerly known as the Federal Inland Revenue Service (FIRS), an assessment tax totalling N2 billion.
The order was delivered by a five-member panel in its judgment on Appeal No. TAT/ABJ/332/2023, filed by the Institute. The panel comprised Chief Moremi Soyinka-Onijala, Anthony Amoman, Dr Chukwudi Ezeudeka, Dr Gbenga Falana and Amina Ibrahim.
CTIN had filed the suit on September 7, 2023, challenging a notice of additional assessment and demand notes issued for companies’ income tax, education tax, and withholding tax covering the 2018 to 2020 years of assessment and the 2017 to 2019 years of account, alongside a notice of refusal to amend, dated September 2023.
The Institute argued that the charges imposed on companies’ income tax and education tax relating to interest income earned on its Treasury Bills, Bonds, and Fixed Deposit placements were unlawful, null and void, and inconsistent with existing legal provisions. It further contended that the withholding tax levied on management fees paid to the Bank of Industry was equally unlawful.
In resolving the matter, the panel identified four key issues for determination: whether the appellant's activities constituted a trade or business, given that income is not the same as taxable profit; the applicability of the Companies Income Tax (Exemption of Bonds and Short-Term Government Securities) Order, 2011; matters relating to education tax; and issues concerning withholding tax.
Delivering the judgment, Soyinka-Onijala stated that after carefully considering the statutory duties and obligations of all parties involved in the transaction underlying the appeal, the Tribunal proceeded to recompute the Company Income Tax and Tertiary Education Tax payable by the appellant.
"In carrying out the recomputation, the Tribunal allowed as a deductible expense the management fees paid by the Appellant to the Bank of Industry and accordingly deducted the said fees from the interest income in order to arrive at the revised assessable profit and total profit," she said.
The Tribunal further noted that, in line with the provisions of the Companies Income Tax Act (CITA), the Bank of Industry is required to deduct withholding tax at the applicable rate of 10 per cent from the interest income at source and remit it to the respondent. "Due credit has therefore been given for the withholding tax so deducted in determining the Appellant's final CIT liability," the panel held.
Consequently, the Tribunal determined that the Companies Income Tax payable by the appellant stands at N1,835,484,959.69, while the Tertiary Education Tax payable amounts to N190,158,410.44.
On the whole, the Tribunal held that the appeal fails and is accordingly dismissed, save for a limited exception. It directed the respondent to recompute the assessment within 30 days to reflect the exemption of interest income specifically traceable to Federal Government Treasury Bills and Bonds, in line with the Companies Income Tax (Exemption of Bonds and Short-Term Government Securities) Order, 2011.
Written by
Atlantic Reports Admin
Comments
- Be the first to comment.